Deal BreakdownJul 21, 2026
This Cleaning Business Leaves $194K After Debt. So Why Is It So Cheap?
The valuation is attractive, the debt coverage is excellent, and the business co...
40 years of history… priced like it prints money.
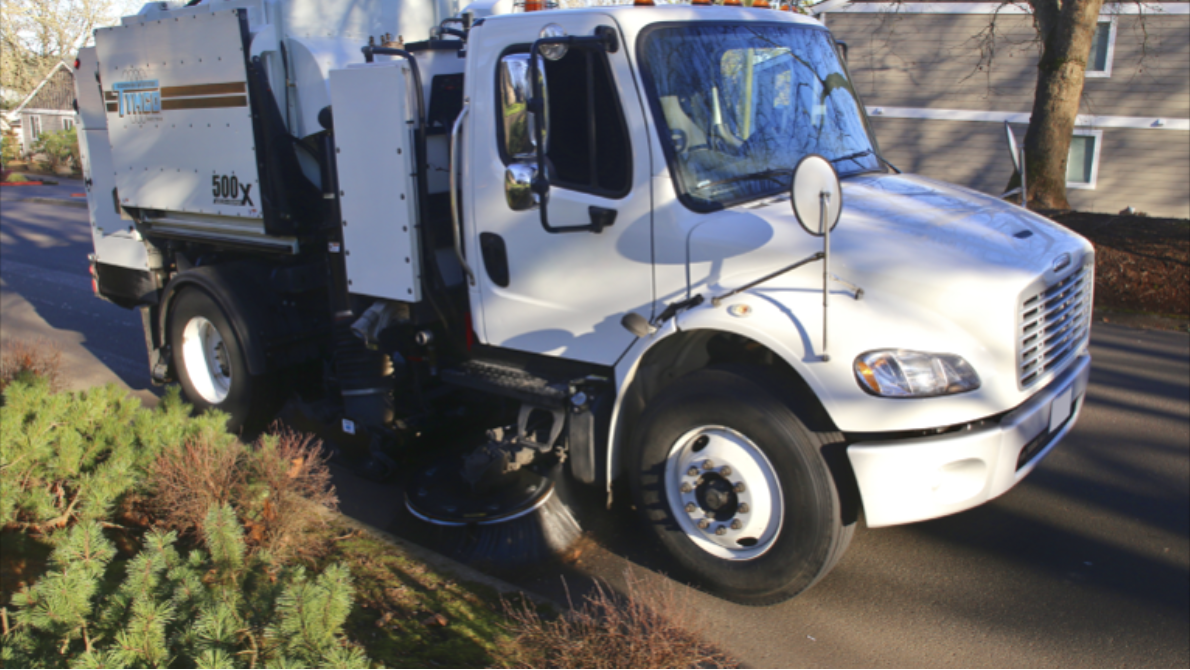
This street sweeping business is listed at $4.6M, doing about $2.4M in revenue and $500K in cash flow.
It’s been around for over 40 years, with long-term contracts and a niche service offering.
Sounds solid — until you run the numbers.
Let’s look at what happens under a real financing scenario.
At standard SBA terms, this deal does not qualify.
To even get close, you’d need to bring over $2.1M upfront.
Even after forcing the deal to work… the returns are terrible.
You’re tying up over $2 million… to make $100K.
That’s not a business — that’s a bad bond.
This is where the deal completely breaks.
That’s not a premium.
That’s a disconnect from reality.
You’re not even getting the full asset base.
So you’re paying top dollar… without owning the foundation.
Strip away the story, and here’s what’s left:
The business itself is fine.
The deal structure is not.
This deal scores a 2.5 / 10.
Strong history and niche — but completely broken economics.
You’re not investing in upside.
You’re funding someone else’s retirement at peak pricing.
Want to catch deals like this before they burn you? Run your own numbers →
Want to see the original listing? View it here →
See how reported Cleaning sale prices and transaction volume compare with this listing.
The valuation is attractive, the debt coverage is excellent, and the business co...
One of our followers submitted this commercial cleaning business and asked a gre...
If I had to buy one type of boring business tomorrow, commercial cleaning would...