Deal BreakdownJul 21, 2026
This Cleaning Business Leaves $194K After Debt. So Why Is It So Cheap?
The valuation is attractive, the debt coverage is excellent, and the business co...
Strong assets and insurance relationships, but the deal math is ugly.
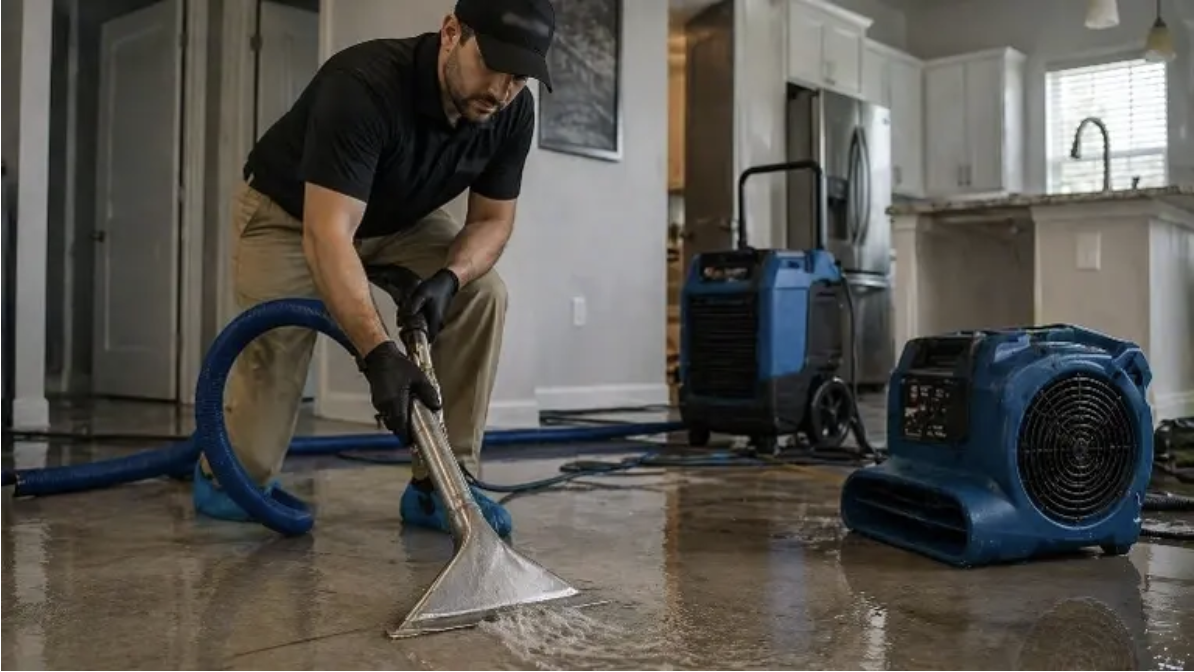
This restoration company in Greater Orlando is listed at $1.2M, generating about $1.1M in revenue and $262K in cash flow.
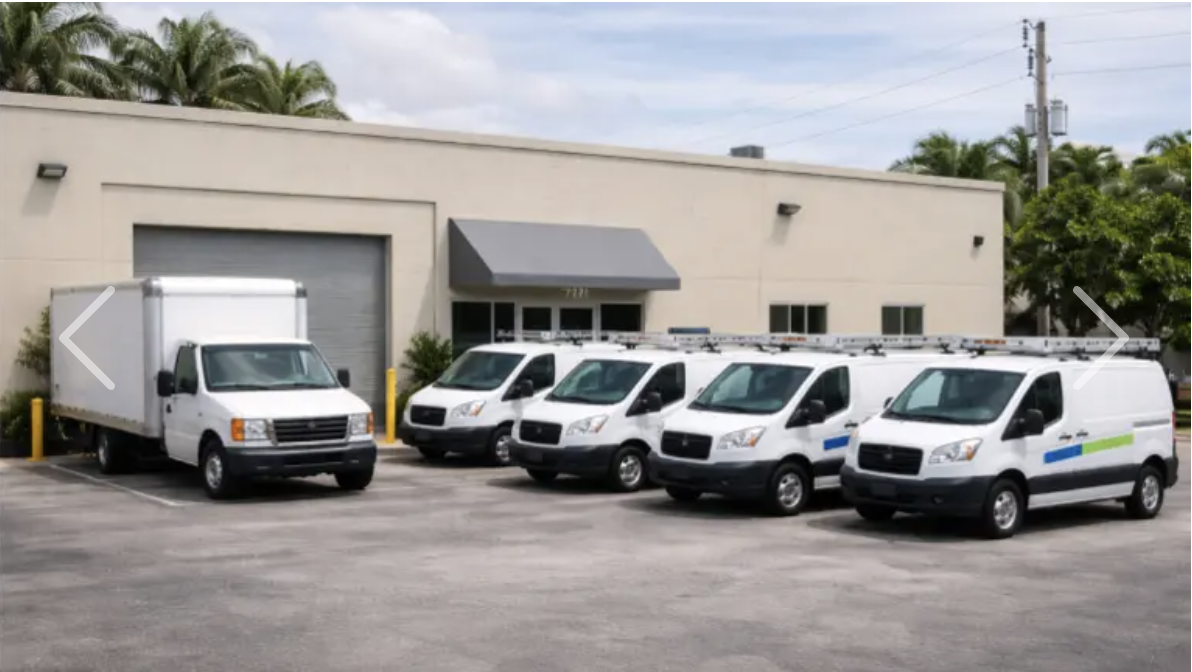
It has insurance-driven revenue, preferred vendor relationships, and over $512K in included assets.
That sounds strong - until you run the deal through financing.
Here is what you actually keep:
You are buying a million-dollar business to make about $84K per year after debt.
That is the problem.
The valuation does not match the performance.
They are asking for premium pricing without premium performance.
There are positives here.
But assets and relationships do not fix a bad valuation.
This business was only established in 2023.
That means you are paying a premium multiple for a business with a very short operating history.
In restoration, relationships, crews, response time, and insurance workflows matter. Two years is not enough history to blindly trust the numbers.
This is an asset-heavy business priced like a proven platform.
That is not enough to justify the price.
This deal scores a 4.3 / 10.
Not because restoration is a bad industry - but because this deal is priced too aggressively for the cash flow, margin, and track record.
Premium price. Short history. Weak take-home.
Want to pressure test deals like this? Run your numbers →
Want to see the original listing? View it here →
See how reported Cleaning sale prices and transaction volume compare with this listing.
The valuation is attractive, the debt coverage is excellent, and the business co...
One of our followers submitted this commercial cleaning business and asked a gre...
If I had to buy one type of boring business tomorrow, commercial cleaning would...