
Deal BreakdownApr 8, 2026
A Clean Deal - But Not a Simple One
Strong cash flow, fair pricing… but execution still matters.
This manufacturing business has solid financials, but its biggest selling point isn't the revenue. It's the patents.
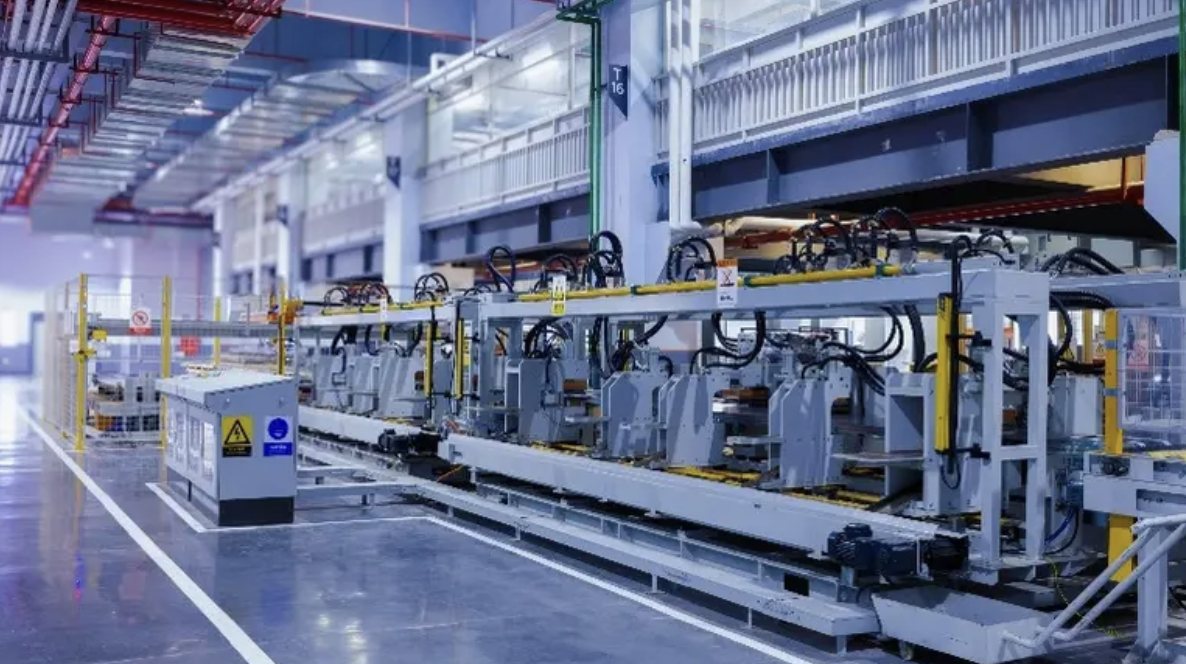
At first glance, this looks like a quality manufacturing business.
The company manufactures specialty adhesive products using proprietary technology that the listing claims is protected by patents, creating meaningful barriers to entry.
The financials also look strong, but intellectual property can be difficult to value without digging deeper.
Now let's run the deal through a standard SBA financing scenario.
After debt payments, the buyer is left with roughly $186K per year. Combined with a DSCR above 2.2, the financing looks very comfortable.
Exactly how much of the company's competitive advantage comes from the patents?
I'd want to review the patent portfolio, confirm expiration dates, understand whether any infringement challenges exist, and determine how difficult it would be for a competitor to develop an alternative solution.
If the patents truly create a durable moat, paying a small premium may be justified. If they do not, the valuation becomes much harder to defend.
BizHub scores this deal a 8.3 / 10.
Strong margins, comfortable debt coverage, and proprietary technology make this one of the stronger manufacturing businesses we've reviewed.
The biggest question isn't whether the business is profitable.
It's whether the patents are still creating the competitive moat the seller says they are.
Want to pressure test deals like this yourself? Try the BizHub Deal Calculator →
Want to see the original listing? View it here →
See how reported Other Manufacturing sale prices and transaction volume compare with this listing.