Deal BreakdownJul 20, 2026
This Laundromat Looks Cheap. But One Missing Detail Could Change The Entire Deal
The valuation is below industry averages, the debt coverage is strong, and the b...
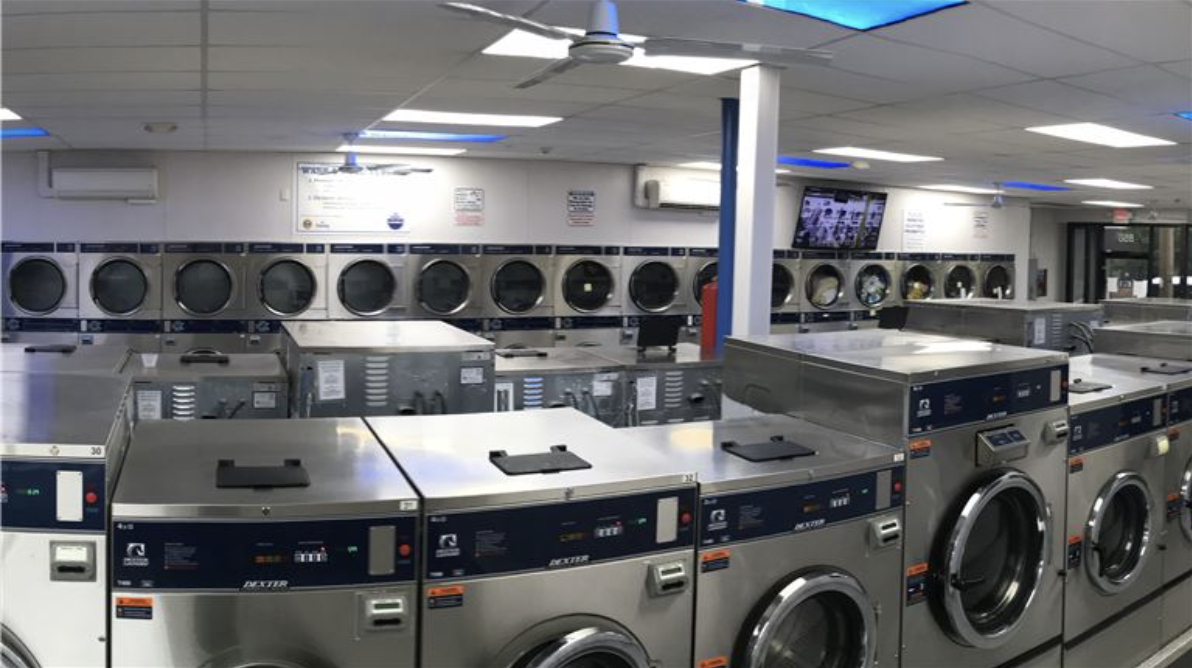
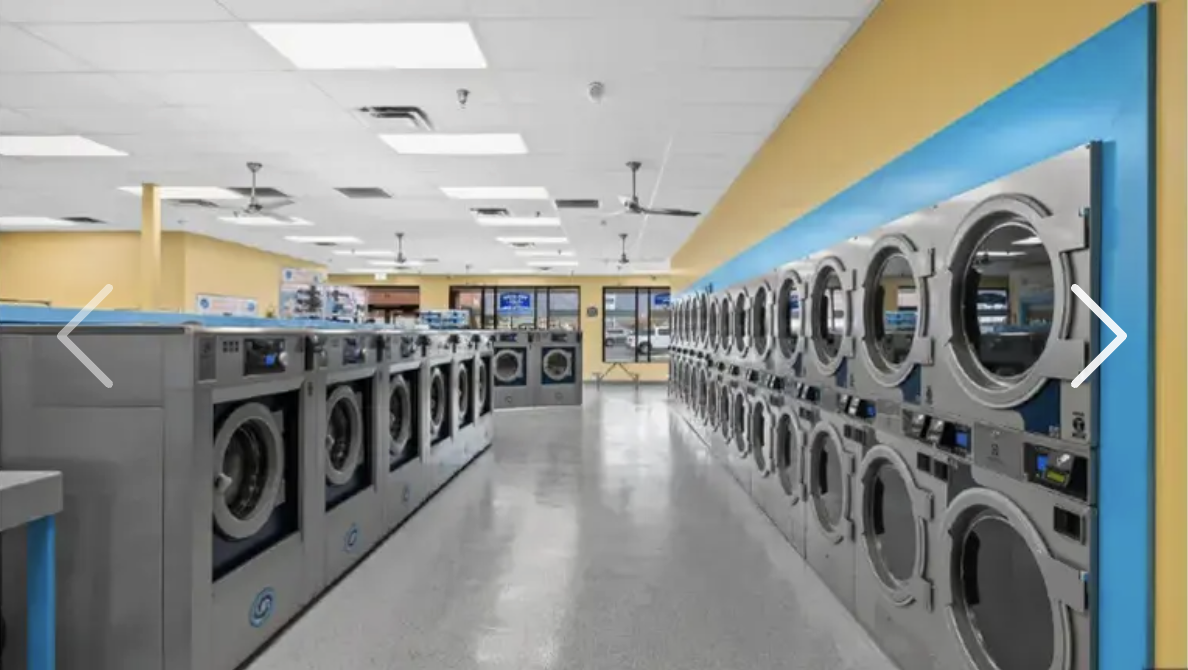
This laundromat is completely brand new, but is it actually a good buy?
It’s listed at $2.95 million, with $421K in cash flow on about $890K in revenue.
And the listing keeps emphasizing things like brand new equipment, absentee ownership, long-term lease control, and infrastructure-style cash flow.
Sounds great.
But when we run it through the BizHub calculator, the numbers completely change the story.
After loan payments, you’re left with only about $84K a year in cash flow.
But here’s the real kicker.
This deal doesn’t qualify with only 10% down because the DSCR falls below lender minimums.
To make the SBA debt work, you’d need to put down almost $900K — or nearly 30%.
You’re taking on nearly $3 million of purchase price risk for returns that barely justify the equity.
Now to be fair, the margins are strong at about 47%, and the equipment is basically brand new.
The lease structure is also unusually long for a single laundromat location, with roughly 30 years of total site control.
And because the store was built from the ground up in 2024, there’s likely very little near-term capital expenditure risk.
Which is probably why they’re trying to command a 7x cash flow multiple.
But laundromats are usually valued as stable cash-flow assets — not venture-style growth stories.
And this business has almost no long-term operating history.
The BizHub score lands around a 3 out of 10.
Nice asset. Probably terrible buy at this price.
If the numbers only work when you bring nearly a million dollars down, the valuation is the problem — not the business.
Want to see the original listing? View it here →
Model the financing, debt service, DSCR, post-debt cash flow, and valuation multiples using your own assumptions.
The valuation is below industry averages, the debt coverage is strong, and the b...
Three locations, strong story… but the math completely breaks.
Great margins, solid cash flow… but the lease can change everything.